A fintech seed round is usually the first time a founder raises serious outside money on proper terms, and this guide sets out 10 practical steps to plan, run and close one. Seed investors in fintech look at the same things as other investors, such as the team, the market and early traction, but they also want to know that you understand regulation, partner banks and the cost of compliance before they commit.
The market is open but selective. Crunchbase News reported in July 2026 that fintech startups raised $28.6 billion globally in the first half of 2026, up 22.7% on the same period in 2025, with Y Combinator the most active seed investor in the sector in the second quarter. Money is there for well-prepared companies; the steps below are about being one of them.
We run FinNext, a one-day fintech summit with editions in Dubai, London and Singapore, where investor meetings and founder introductions are part of every edition. The advice applies wherever you raise.
In this article
What a fintech seed round is and what investors expect
A seed round is a startup’s first institutional raise, typically after pre-seed money from the founders, angels or an accelerator. It funds the work needed to reach the milestones that make a Series A possible: a working product, paying customers or committed partners, and evidence that the business model can scale.
In fintech, investors add a further layer of questions. Who holds the licence? Which bank or e-money partner sits behind the product? What does compliance cost each month, and how long before a regulator approves you? A founder who can answer these clearly removes a large part of the perceived risk.
Seed investors in fintech usually look for:
- A team with financial services knowledge and the technical skill to build.
- A clear problem for a defined customer, with evidence that customers will pay.
- A credible route to regulatory approval, or a partner that already holds the licence.
- Early traction: pilots, a waiting list, transaction volumes or revenue.
- A plan for what the money will achieve, and by when.
Prepare before you pitch: steps 1 to 4
1. Decide what the seed money must prove
Start with the milestones, not the amount. Write down the three or four things the business must show by the time you raise again, such as a licence granted, a bank partnership live, a target number of active users or a level of monthly revenue, and how long each will take.
Those milestones become the spine of your pitch. They tell investors what they are paying for, and they give you an honest basis for sizing the round in step 4.
2. Map your regulatory path early
Regulation shapes both your timeline and your burn rate, so investors will ask about it in the first meeting. Decide whether you will apply for your own licence, operate under a partner’s licence or start in a regulatory sandbox, and be ready to explain why.
Timelines vary by market. In the UK, the FCA said in July 2025 that it was proposing faster authorisation deadlines: four months for complete applications from new firms, down from six, and ten months for incomplete ones, down from twelve, plus a voluntary three-month target for complete payments and e-money applications.
In the Dubai International Financial Centre (DIFC), the DFSA’s Innovation Testing Licence lets eligible firms test products under a restricted licence; the regulator said in May 2025 that decisions typically come 10 to 12 weeks after a complete application. In Singapore, the MAS Sandbox Express guidelines set a target of responding within 21 days to complete applications for the activities they cover.
3. Choose the right instrument: SAFE, convertible note or priced round
Seed money usually comes in one of three forms. A SAFE (simple agreement for future equity) and a convertible note both give investors the right to shares later, normally at a capped valuation or a discount, without setting a price today. A priced round sells shares now at an agreed valuation, with fuller legal documents.
SAFEs are common in the US: Carta reported in July 2025 that 82% of nearly 120,000 SAFEs signed on its platform used the post-money version that Y Combinator published in late 2018. Practice differs by country, so ask a local lawyer which instrument investors in your market expect, and how it interacts with any tax schemes they use.
4. Size the round and model dilution honestly
Work out how much you need to reach your milestones, then add a buffer, because regulatory approvals and bank integrations often take longer than planned. The aim is enough runway to hit the milestones with time left to raise the next round.
Then check the dilution. Carta’s data on 5,118 priced rounds raised by US startups in 2025 put median seed dilution at 19.5%, and fewer than 10% of seed rounds sold 30% or more of the company. These are US figures, but they are a useful reference when an offer looks out of line.
Build a simple cap table model showing founder ownership after this round and an assumed Series A, including the option pool. Investors will do this maths; do it first.
Find and approach the right investors: steps 5 to 7
5. Build a targeted list of fintech investors
A focused list of investors who back your stage, sector and region beats hundreds of random names. For each one, note the typical cheque size, recent fintech deals, whether they lead rounds and the partner who covers your area. Funds that publish a thesis on payments, wealth, insurance or infrastructure are easier to match.
Most fintech fundraising draws on a mix of these sources:
- Angels with financial services experience, who often bring introductions as well as money.
- Accelerators and seed funds that specialise in fintech.
- Corporate venture arms of banks, insurers and payment companies, which can add distribution but may move more slowly.
- Government-backed co-investment schemes and tax-advantaged angel programmes in your market.
6. Get warm introductions and use events well
A warm introduction from a founder in the investor’s portfolio, an angel or an adviser they trust gets a far better response than a cold email. Make it easy: send a short, forwardable note covering what you do, your traction and how much you are raising.
Events compress weeks of outreach into a day. Book meetings in advance, keep a one-line and a 30-second introduction ready, and follow up within 48 hours. Our guide to fintech conference networking covers how to plan those meetings in detail.
7. Tell a fintech story investors can underwrite
Keep the deck short and specific: problem, customer, solution, traction, business model, market, regulatory path, team, and the round with its milestones. Fintech investors look closely at unit economics, such as revenue per transaction or per account against the cost of acquiring, verifying and serving each customer.
Show the risks you have already removed. A signed partnership letter, a sandbox admission or a live pilot with a bank is more persuasive than a large market-size figure.
Run the process and close: steps 8 to 10
8. Prepare a clean data room before the first meeting
Investors who like the first meeting will ask for documents quickly, and slow answers suggest disorganisation. Have a data room ready with:
- Company documents and an up-to-date cap table.
- The financial model and the latest accounts.
- A product, security and data protection overview.
- Regulatory status: licences, applications and key correspondence.
- Key contracts with banks, partners and customers.
- Intellectual property assignments from founders and contractors.
9. Run a tight, time-boxed process
Batch your first meetings into a few weeks so that interest builds at the same time. A drawn-out raise lets momentum fade and invites the question of why nobody has committed yet.
Track every conversation in a simple pipeline: contacted, first meeting, follow-up, due diligence and term sheet. Keep existing angels updated as you go; they can often help bring in the last part of the round.
10. Negotiate the terms that matter, then close
Valuation matters, but so do the terms around it: the size of the option pool, liquidation preference, pro rata rights, board seats and information rights. A clean term sheet at a fair valuation is often worth more than a higher headline number with heavy conditions.
After the term sheet come the legal documents and confirmatory checks. Use lawyers who know venture deals, agree a closing timetable, and keep running the business; investors notice whether you hit the numbers you showed them.
Seed funding support in the UK, UAE and Singapore
Each of the three FinNext cities offers schemes or regulatory routes that can make a seed round easier. The table gives a few examples; check the official pages for the current rules.
| Market | Example | What it offers |
|---|---|---|
| UK | Seed Enterprise Investment Scheme (SEIS) | Companies can raise up to £250,000; investors can get up to 50% income tax relief on up to £200,000 a year |
| UK | FCA authorisation | Proposed statutory deadline of four months for complete new-firm applications |
| UAE (DIFC) | DFSA Innovation Testing Licence | A restricted licence to test products, with decisions typically in 10 to 12 weeks |
| Singapore | Startup SG Equity | Government co-investment alongside qualified third-party investors in eligible early-stage deep tech startups |
SEIS has further conditions. According to GOV.UK, the company must have gross assets of no more than £350,000 and fewer than 25 full-time equivalent employees when the shares are issued, and HMRC offers advance assurance on whether a share issue is likely to qualify. The British Business Bank summarises the investor reliefs.
Startup SG Equity is aimed at companies with research-based intellectual property, so it suits only some fintechs. In March 2026, Enterprise Singapore announced a further S$1 billion for the scheme, extending support to growth-stage deep tech startups.
Common fintech fundraising mistakes to avoid
- Raising before the regulatory path is clear.
- Pitching investors who never back companies at your stage.
- Underestimating compliance costs and the time to a licence.
- Accepting heavy terms in exchange for a headline valuation.
- Letting the process drag on for months.
- Pausing customer work while you raise.
Most of these share a root cause: treating the raise as a project separate from the business. The strongest seed funding rounds come from companies that keep shipping and selling while they talk to investors.
This article is general information, not legal, tax or financial advice; check the regulator’s and tax authority’s current rules and take professional advice before you raise.
Facts checked on 4 November 2026.
Fintech seed round: frequently asked questions
How much should a fintech startup raise in a seed round?
There is no single right amount. Size the round from your milestones: what you need to prove before a Series A, how long that will take, and a buffer for delays. Regulated models often need more capital than pure software because of licensing and compliance costs.
How much equity do founders usually give away at seed?
Carta’s data on priced seed rounds raised by US startups in 2025 put median dilution at 19.5%, and fewer than 10% of rounds sold 30% or more of the company. Terms vary by market, so model your ownership through to a Series A before you agree a deal.
Do I need a licence before raising a fintech seed round?
Not always. Many fintechs raise seed money while applying for a licence, working under a partner’s licence or testing in a regulatory sandbox. What investors want to see is a credible, costed plan for getting approval.
Should I use a SAFE or a priced round?
SAFEs and convertible notes are quicker and cheaper to agree and are common in the US, while a priced round sets a valuation and gives investors shares straight away. The right choice depends on what investors in your market expect and on any tax schemes they use, so take local legal advice.
Can fintech events help with fundraising?
Yes, if you prepare. Book investor meetings before the event, bring a clear introduction and follow up within 48 hours. FinNext sets aside time for investor meetings and founder introductions at every edition.
Join us at FinNext 2027
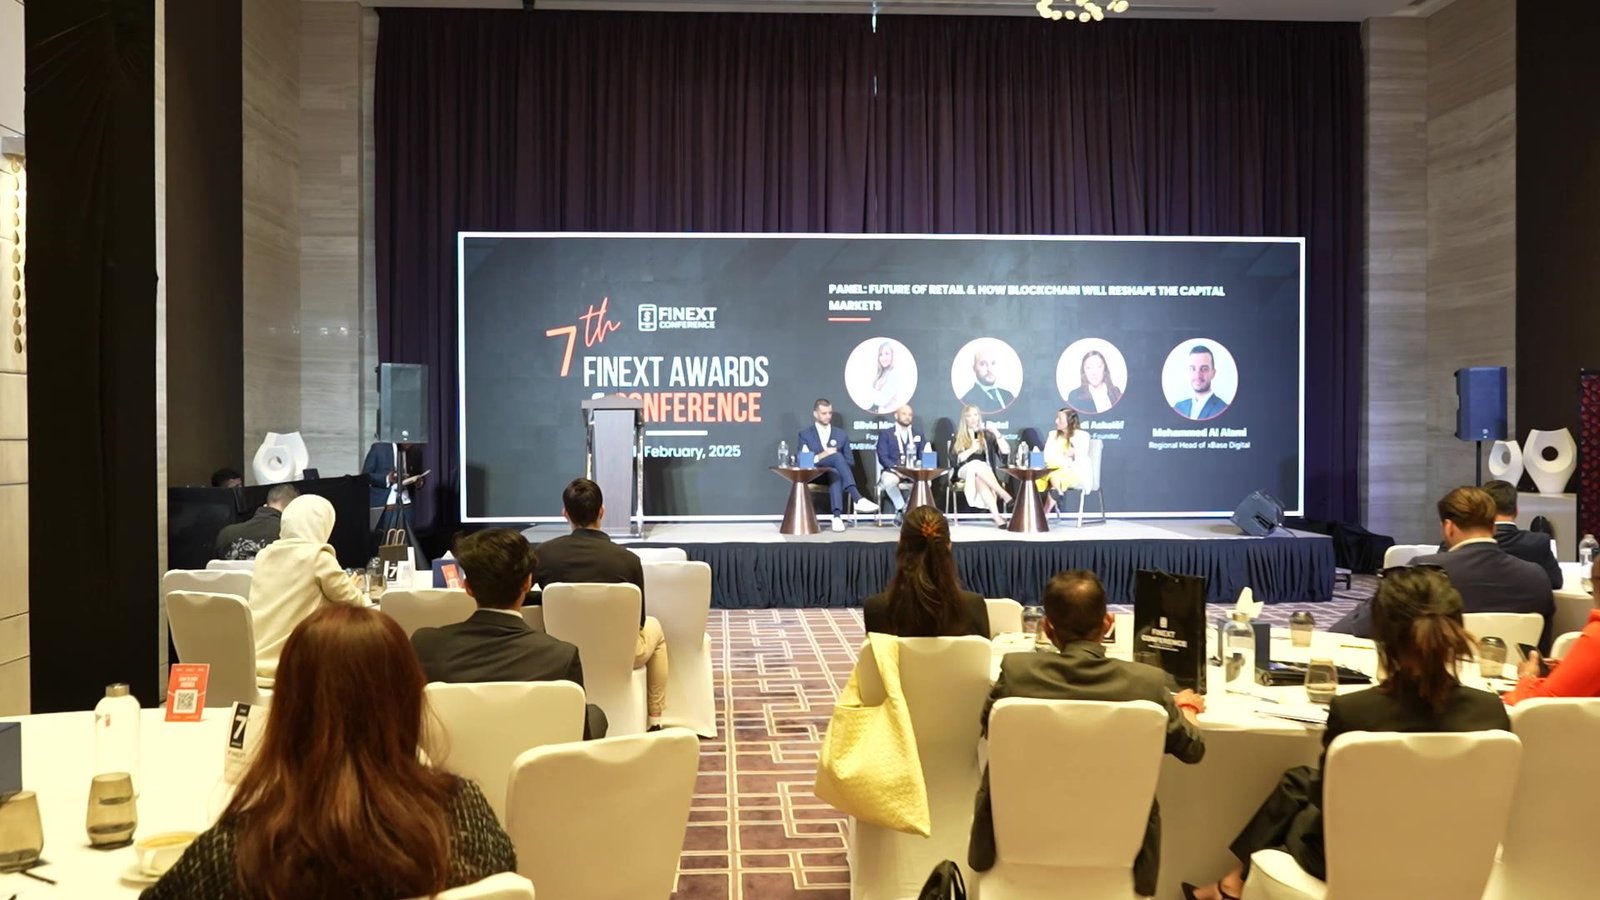
Meet investors, bankers and fellow founders at FinNext 2027 in Dubai on 7 October, London on 13 October or Singapore on 24 November. Get your pass, explore the three editions, or read our guide on how to choose the right fintech conference for your goals.